

What it means when we say profit is not enough
Why raw profit is intuitively appealing, Why Profit Alone Is a Poor Performance Metric
Profit is easy to understand: a single number summarizes how much money an approach made over a period, which explains why many reports lead with it. That simplicity can be useful for a headline, but it hides how returns were produced and how much risk was taken to get them. For decision making we need measures that account for variability and the chances of large losses, not only total gains, because two strategies with equal profit can present very different risk profiles.
Raw profit alone does not control for capital base, leverage, or position sizing, so presentational parity is false when those factors differ. The practitioner guidance is to place profit alongside risk measures to avoid misleading comparisons, and to document the observation window used for each result Morningstar risk-adjusted return guide.
reproducible checks for calculating risk adjusted metrics
follow documented code versions
Why does this matter in sports prediction or funded challenge settings? Simple: leverage and aggressive sizing can inflate short term profit while exposing the account to outsized drawdowns later, and short evaluation windows can make luck look like skill. A clear comparison requires normalizing for starting capital, limiting leverage or documenting it, and using a long enough sample to observe variability and rare losses.
Concrete ways raw profit can mislead performance comparisons
Leverage and position sizing examples
Increasing leverage or position size can magnify both wins and losses, so a strategy that posts higher profit because it used larger bets may look better on headline metrics while being riskier to hold. Without a measure of volatility or drawdown, profit does not reveal the degree to which outcomes depended on aggressive exposure, which is critical for fair evaluation Morningstar risk-adjusted return guide.
In simulated funded accounts, conceptual examples illustrate how a high profit path that used doubling of stakes after wins will diverge sharply in tail outcomes compared with a steady position sizing plan, even if cumulative profit ends the same. That divergence matters for real users who must respect drawdown rules or capital limits.
Short sample bias and lucky streaks
Short evaluation windows amplify the chance that a lucky sequence of outcomes produces a strong cumulative profit number that will not persist once the sample grows. This short sample bias is a common source of misinterpretation, because early results are more volatile and more likely to include flukes that change rankings when more data arrives CFA Institute practitioner guidance.
For sports prediction challenges with structured time limits, a short streak can make a participant appear superior even though longer horizons would reveal regression toward expected edges. Evaluators should therefore treat short evaluation periods cautiously and prefer longer samples when possible.
How tail events skew perception
Return distributions that are skewed or fat tailed will create situations where occasional large wins drive cumulative profit while leaving frequent small losses unaddressed. That pattern can make profit look attractive while hiding the strategy s exposure to rare, large losses that matter to account survivability. Recognizing tail risk requires metrics that emphasize downside behavior rather than aggregate gains Morningstar risk-adjusted return guide.
In short, profit is a one dimensional summary. To compare strategies fairly you must control for leverage, normalize for capital and use samples long enough to observe volatility and extreme outcomes.
Why risk adjusted metrics give better comparability
Core idea: returns per unit of risk
Risk adjusted metrics recast performance as how much return is earned for each unit of risk taken, which makes cross strategy comparisons meaningful even when capital bases or volatility differ. This framing lets an evaluator prefer a lower profit stream that achieved its gains with less variability if capital preservation is important, or prefer higher volatility for an investor who tolerates drawdown for higher upside.
Different metrics capture different notions of risk, so a complete summary uses several complementary measures rather than a single ratio Morningstar risk-adjusted return guide.
Compare strategies using risk adjusted measures like Sharpe and Sortino together with maximum drawdown, win rate and payoff ratio, and use reproducible methods and sufficiently long samples to avoid short sample bias.
When should you prefer volatility based measures like Sharpe, and when should you focus on downside focused metrics like Sortino? The answer depends on whether positive variability is acceptable, and on the asymmetry of the return distribution.
When to prefer volatility versus downside-focused measures
Volatility based measures treat upside and downside variability equally, which is fine when returns are symmetric and an investor sees unpredictability in either direction as costly. By contrast, downside-focused measures only penalize returns that fall below a chosen threshold, which aligns better with objectives that prioritize avoiding losses over capturing upside variability Investopedia Sortino ratio explanation.
Practical comparability is achieved by reporting both types of metrics side by side so that readers understand whether a high ratio comes from stable moderate gains or from frequent small wins and occasional large payouts.
Why multiple metrics are essential
No single metric fully describes performance. Volatility, downside deviation and drawdown each tell part of the story. Presenting them together with basics such as sample length and trade frequency gives an evaluator the context needed to judge whether a strategy s profile matches an operational constraint or a challenge rule set CFA Institute practitioner guidance.
Later sections describe how to combine Sharpe, Sortino and maximum drawdown into a decision checklist for funded challenge selection and reporting.
Sharpe ratio: what it measures, strengths and limits
Definition and simple formula
The Sharpe ratio measures excess return per unit of total volatility. At a high level it is the difference between the strategy s average return and the risk free rate, divided by the standard deviation of returns, which converts raw profit into a risk adjusted figure useful for comparison across strategies Sharpe original paper.
In plain language, Sharpe tells you how much reward you received for the amount of overall variability in returns; higher values indicate more return per unit of variability under the ratio s assumptions.
When Sharpe is appropriate
Sharpe works best when return distributions are roughly symmetric and there are no extreme tail outcomes that dominate long term results. Under those conditions total volatility is an informative proxy for the kind of risk that matters to many investors and strategy evaluators Morningstar risk-adjusted return guide.
For sports prediction portfolios that produce fairly steady, small variations around an expected edge, Sharpe can be a convenient starting metric, but it should not be the only metric used.
Pitfalls with skewed or fat tailed returns
When returns are skewed or fat tailed, Sharpe may mis-rank strategies because standard deviation treats upside surprises the same as downside stress, and extreme events can distort the standard deviation in ways that do not reflect downside exposure adequately. That is an important limitation for many prediction strategies that produce asymmetric payoffs Sharpe original paper.
Practitioners should therefore examine return histograms, tail quantiles and drawdown behavior alongside Sharpe to avoid overreliance on a single number.
Sortino ratio: focusing on downside risk
Definition and difference to Sharpe
The Sortino ratio switches the denominator used in Sharpe from total standard deviation to downside deviation, which measures variability only from returns that fall below a defined target or floor. By focusing on downside variability it avoids penalizing volatility that comes from returns above the target, giving a clearer picture when upside swings are acceptable and downside outcomes are the primary concern Investopedia Sortino ratio explanation.
Because Sortino concentrates on negative outcomes, it is often preferred when protecting capital or avoiding failure states matters more than capturing extra upside.
Download the reproducible performance checklist and methodology guide
Download the checklist or method guide to run consistent Sortino and drawdown checks, and follow documented steps for reproducible results.
When Sortino gives a clearer picture
Sortino is especially useful when returns are asymmetric, or when reward managers want to avoid penalties for variability produced by positive spikes. In those contexts a higher Sortino communicates that downside behavior is controlled even if total volatility is elevated due to favorable outliers.
It is important to define the target return or threshold used to compute downside deviation, because that choice affects interpretation and comparability across reports.
How to compute downside deviation
Downside deviation is computed by isolating the returns below a chosen threshold, squaring their shortfall from that threshold, averaging across the sample, and taking the square root, with appropriate annualization for the return frequency. Clear documentation of the threshold and frequency is essential for reproducibility and fair comparison Investopedia Sortino ratio explanation.
Because Sortino focuses on negative variation, it requires enough data on losses to produce a stable estimate, so short samples can produce noisy downside deviation figures that should be interpreted with caution.
Maximum drawdown and path dependent risk
Definition and why it matters
Maximum drawdown is the largest observed peak to trough loss in a return series over a specified interval, and it directly reports the worst capital loss an investor would have experienced during that window. That makes it especially useful to understand survivability under stress and to set operational limits such as stop out or reset rules Investopedia maximum drawdown guide.
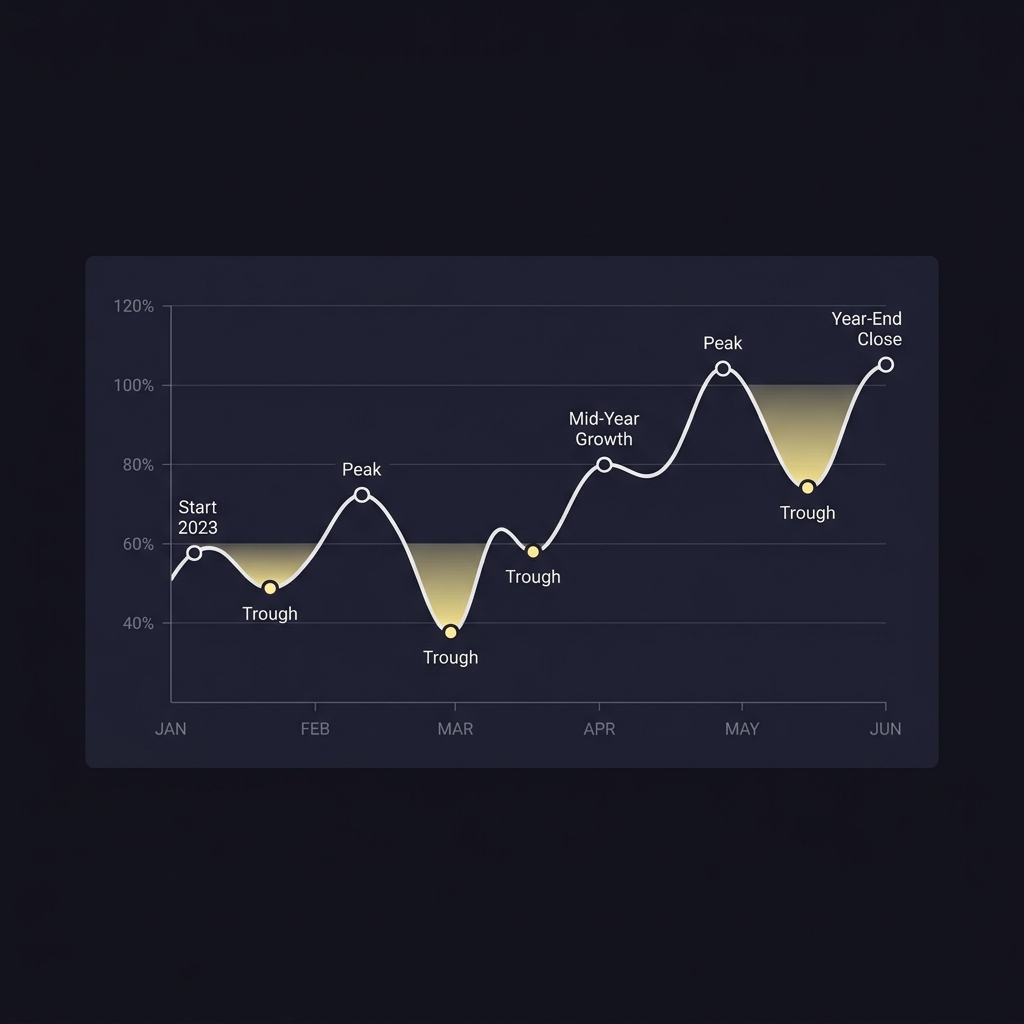
Unlike volatility measures, drawdown is path dependent: the same set of returns can produce different maximum drawdowns depending on their order, so drawdown captures risk that aggregate statistics can miss.
How MDD complements volatility metrics
Maximum drawdown highlights worst case observed declines and therefore complements volatility ratios that summarize average variability. A strategy with high Sharpe but deep MDD may be unsuitable for participants who must meet drawdown caps, while a lower Sharpe with shallow MDD might be operationally preferable under strict capital rules Investopedia maximum drawdown guide.
Reporting both types of measures together lets evaluators see whether attractive risk adjusted returns are achieved with manageable peak losses or at the cost of intermittent large declines.
What MDD reveals about capital at risk
Maximum drawdown directly communicates how much of the account could have been lost during the worst episode in the observed sample, which is a concrete quantity for operators and participants who face hard limits. It is therefore indispensable in challenge environments that enforce drawdown thresholds or recovery rules Investopedia maximum drawdown guide.
Because MDD is path sensitive, analysts often show the drawdown series graphically and publish the dates of peak and trough to make stress episodes auditable.
A practical decision framework for comparing strategies
Stepwise checklist for evaluation
Start with a reproducible checklist: normalize returns to a common capital base, document leverage and position sizing rules, select an appropriate lookback period, compute annualized mean return, compute volatility and downside deviation, build a drawdown series and report maximum drawdown, then add context metrics such as win rate and payoff ratio. This stepwise approach creates comparable summaries across strategies and supports informed selection Morningstar risk-adjusted return guide.

When combining metrics, interpret patterns rather than single numbers: a high Sharpe with a large maximum drawdown suggests episodic stress masked by average behavior, while a modest Sharpe with small drawdowns indicates steady management of downside risk. Include win rate and payoff ratio to distinguish many small winners from fewer large payoffs, which helps explain why strategies with similar ratios can feel different to an operator. Record these combinations with the sample length and frequency used, so others can reproduce the judgments and testers can retest under the same rules.
How to combine Sharpe, Sortino and MDD
Use a matrix: if Sharpe and Sortino are both high and MDD is low, the strategy is broadly attractive; if Sharpe is high but Sortino low, investigate skewness and downside exposure; if Sortino is high but Sharpe low, the strategy likely tolerates upside variability while controlling losses. This combined view clarifies which metric is driving apparent strength and what operational risks remain Morningstar risk-adjusted return guide.
Record these combinations with the sample length and frequency used, so others can reproduce the judgments and testers can retest under the same rules.
Context metrics to add: win rate and payoff ratio
Win rate and payoff ratio provide behavioral context: win rate counts how often predictions produce positive outcomes, while payoff ratio measures average gain on wins relative to average loss on losses. Together they explain whether profit came from consistent small edges or from infrequent large wins, which informs risk management and position sizing decisions CFA Institute practitioner guidance.
Including these context metrics alongside Sharpe, Sortino and MDD gives a fuller picture for sports prediction evaluators and funded challenge administrators.
Reporting best practices and sample length considerations
Minimum sample guidance and regime awareness
Report metrics over multiple sample lengths, such as one year, three years and the full history, to show sensitivity to regime shifts. Short windows increase noise and the chance that luck dominates the result, so prefer longer samples for final judgments where available CFA Institute practitioner guidance.
Regime awareness means checking whether results arise from a single favorable period that may not repeat; run subperiod analyses to detect such dependencies and disclose them.
Transparent methodology and reproducible calculations
Publish the exact steps used to compute each metric, including return frequency, how annualization was done, the risk free rate chosen, and any smoothing or outlier treatment. Documented methods enable audit and reduce the chance of inconsistent comparisons across reports PerformanceAnalytics reference manual.
Version control for code and data snapshots is a best practice that helps avoid later disputes about reported numbers.
How to present multiple metrics coherently
Use a compact table that lists annualized mean return, Sharpe, Sortino, maximum drawdown, win rate and payoff ratio for each strategy, and accompany it with a short narrative interpreting tradeoffs. Visuals such as cumulative return and drawdown plots make path dependence and stress episodes immediately visible to readers.
Accompany numeric reports with the raw return series so independent reviewers can recompute metrics and verify conclusions.
Common mistakes and how to avoid them
Overfitting and selection bias
Overfitting occurs when strategy parameters are tuned to past data and do not generalize, inflating apparent performance. Selection bias arises when only the best performing samples are reported while weaker runs are withheld. Both issues can create a misleading picture of skill rather than luck and should be mitigated with cross validation and out of sample testing CFA Institute practitioner guidance.
Publish how parameters were chosen and show out of sample results to demonstrate robustness.
Ignoring path dependence and tail risk
Relying on average metrics alone misses path dependent failures such as long drawdowns or rare catastrophic losses. Include drawdown analysis and tail checks to surface these risks before they surprise stakeholders Investopedia maximum drawdown guide.
Stress tests that replay adverse sequences or increase volatility can reveal vulnerabilities not visible in mean based summaries.
Misusing single metric comparisons
Comparing strategies solely on profit or a single ratio like Sharpe can mislead because each metric answers a different question. Avoid this mistake by using the stepwise checklist and combining complementary measures when communicating performance Morningstar risk-adjusted return guide.
When presenting a single headline number, always follow with context lines that summarize volatility, drawdown and sample length.
Practical scenarios and sports prediction examples
Scenario A: high profit but large drawdowns
Imagine a prediction approach that posts strong cumulative profit over six months but achieves it with aggressive position sizing and occasional large losses. Its Sharpe may look attractive during calm stretches, but its maximum drawdown can be deep enough to fail a funded challenge s drawdown rules. That mismatch underlines why profit alone is an unreliable ranker Morningstar risk-adjusted return guide.
In practice an evaluator would flag such a strategy for closer stress testing and examine the drawdown dates to judge whether the decline resulted from identifiable regime change or from structural tail exposure.
Scenario B: steady low profit with favorable downside metrics
Contrast that with a steady, lower profit series that shows modest volatility, high Sortino, and shallow maximum drawdown. Though headline profit is smaller, the consistent profile may be preferable for participants who must meet drawdown caps or who prefer capital preservation in funded challenges.
Here the combination of Sortino and MDD provides the evidence an operator needs to prefer steadiness over episodic wins.
What to look for in funded challenge evaluations
For funded challenge contexts, prioritize metrics that reflect compliance with account rules: normalized returns, documented leverage rules, maximum drawdown within the allowed cap, and evidence of reproducible methodology. Those checks align performance claims with operational realities and support fair ranking of participants Morningstar risk-adjusted return guide.
Where possible, require submission of the return series and a description of position sizing so reviewers can reproduce reported ratios and drawdowns before awarding progression or rewards.
Step by step calculations and reproducible checks
Computing mean return and annualization
Collect the return series at the chosen frequency, compute periodic arithmetic or geometric mean as appropriate, and annualize by scaling with the number of periods per year. State whether returns are net of fees and whether compounding was used for annualization to ensure consistency across reports PerformanceAnalytics reference manual.
For short samples, report both periodic and annualized figures and note the sensitivity of annualization to the sample length.
Calculating volatility and downside deviation
Volatility is the standard deviation of periodic returns annualized by the square root of periods per year. For downside deviation, select a target return, isolate periods below that target, compute squared shortfalls, average them and take the square root, then annualize in the same manner. Clear reporting of the chosen target and frequency is essential for comparability PerformanceAnalytics reference manual.
Because downside deviation uses only negative deviations, it typically produces a smaller denominator than total volatility when upside variability exists, which increases the resulting Sortino ratio relative to Sharpe for the same return stream.
Building a drawdown series and verifying results
Construct the cumulative return or equity series, compute running peaks, and calculate drawdown at each point as the percent fall from the running peak. The maximum drawdown is the minimum of that series over the sample. Publish the dates of the peak and trough so others can audit the stress episode and reproduce the calculation PerformanceAnalytics reference manual.
Include code, or a reproducible notebook, that shows exactly how returns were handled before metric computation to avoid ambiguity and enable verification.
Tools, packages and workflows for transparent analysis
Open source libraries and their strengths
Open source libraries provide standardized, peer reviewed implementations of the metrics described here and reduce the risk of calculation errors when used responsibly. The PerformanceAnalytics package documents routines for Sharpe, Sortino and drawdown calculations and is a practical reference for reproducible analysis PerformanceAnalytics reference manual.
Using established libraries also helps reviewers reproduce results quickly when the same package and version are cited in a methodology note.
Documenting methodology for audit
Record the library versions, the exact functions and parameter choices used, the preprocessing applied to returns, and the date ranges. This documentation enables auditors to run the same routines and confirm numbers reported in a performance summary PerformanceAnalytics reference manual.
Prefer public repositories or notebooks that can be snapshot and archived alongside reports for later review.
Reproducible report templates
Create templates that include the return series, a small table of reported metrics, the drawdown plot, and a short interpretation. Templates speed review and make it easier to spot inconsistencies between claimed results and the raw data.
Standardized templates reduce the chance of accidental misreporting and support transparent comparisons across multiple entrants or strategies.
Interpreting results and making practical choices
How to select a strategy for a funded challenge
Match metric priorities to the challenge s rules and your risk tolerance: if drawdown caps are strict, prioritize shallow MDD and high Sortino; if allowed leverage is limited but drawdowns are less constrained, a higher Sharpe may be acceptable. Always validate claims with out of sample checks when possible Morningstar risk-adjusted return guide.
Remember that a strategy that sounds good on paper may fail operational constraints such as maximum position sizes or rules about allowed correlations among selections.
Risk tolerance and operational constraints
Document maximum allowed position sizes, how margin or virtual leverage is handled, and what operational responses are expected during drawdowns. These constraints determine which metrics matter most for a particular challenge or participant.
When returns are nonnormal or sample sizes are small, take a conservative stance and require robustness checks before accepting performance claims.
When to prioritize downside measures over aggregate ratios
Prioritize downside focused metrics when capital preservation is central to operations, when returns show skewness, or when rules enforce drawdown limits. In such cases Sortino and MDD give more actionable guidance than Sharpe alone Investopedia Sortino ratio explanation.
Operational rules should be paired with metric thresholds to make selection decisions explainable and repeatable.
Conclusion: a short checklist and next steps
Key takeaways
Profit alone is an incomplete performance metric because it does not show how returns were achieved or what downside exposure was taken. Pair profit with risk adjusted measures such as Sharpe and Sortino, and always report maximum drawdown to expose path dependent stress.
Use documented, reproducible methods and open source tooling to make comparisons transparent and auditable, and prefer longer samples when feasible to reduce short sample bias PerformanceAnalytics reference manual.

A printable checklist to evaluate claims
Normalize capital, document leverage and position sizing, compute annualized return, compute Sharpe and Sortino with stated parameters, build a drawdown series and report maximum drawdown, add win rate and payoff ratio, and publish the raw return series for audit.
Follow the checklist consistently to make fair comparisons across strategies and to make selection decisions explainable to stakeholders.
Profit alone ignores how returns were generated, including leverage, position sizing and path dependent losses, so it can misrepresent comparative risk.
Use Sortino when downside variability matters more than upside swings, or when return distributions are asymmetric and you want to emphasize loss control.
Maximum drawdown shows the worst peak to trough loss and helps ensure strategies meet drawdown caps and survivability rules.
References
- https://www.morningstar.com/markets/risk-adjusted-return
- https://www.cfainstitute.org/en/research
- https://www.investopedia.com/terms/s/sortinoratio.asp
- https://web.stanford.edu/~wfsharpe/art/sr/sr.htm
- https://www.investopedia.com/terms/m/maximum-drawdown-mdd.asp
- https://cran.r-project.org/web/packages/PerformanceAnalytics/PerformanceAnalytics.pdf
- https://www.fundedplays.com/challenges
- https://www.fundedplays.com/blogs/how-fundedplays-evaluations-work
- https://www.fundedplays.com
- https://www.fundedplays.com/blogs
- https://portfoliometrics.net/blog/risk-adjusted-metrics
- https://potomac.com/blog/risk-statistics
- https://papers.ssrn.com/sol3/Delivery.cfm/SSRN_ID2662054_code2424270.pdf?abstractid=2662054&mirid=1