
What we mean by a "winning pick" versus a profitable trade
Why a Winning Pick Can Still Be a Bad Trade
Many sports predictors use simple counts of wins to judge success, but a winning pick in isolation is not the same as a pick that raises long-term net returns. Expected value, not win rate alone, determines whether a decision contributes to portfolio growth; this distinction matters because fees and odds-implied break-evens change the math bettors must beat U.S. SEC guidance on why fees matter.
Definition first: win rate is the share of bets that finish in the bettor's favor. Edge is the expected advantage versus market odds. Expected value, or EV, combines edge, stake size, and probability to predict average return per bet over time. (See a practical guide to expected value.) Net return is the EV after subtracting transaction costs and any sportsbook hold.
Counting wins is misleading because a high hit rate can coexist with negative EV when odds, vig, and stake sizing are considered. A ticket that wins more often can still produce losses if each win is small relative to the average loss, or if fees and hold consistently erase the margin that wins create.
Long-run performance depends on the average EV per dollar risked and the variance around that expectation. A predictor who focuses on isolated wins may miss how small negative edges compound, producing drawdowns that reduce effective growth.
Regulators and investor education resources stress that ongoing fees materially reduce net returns and must be included when assessing any strategy’s profitability. Small, persistent costs shrink margins and raise the threshold a pick must clear to be worthwhile U.S. SEC guidance on why fees matter.
Converting odds to an implied break-even win rate starts with decimal odds: break-even probability is 1 divided by decimal odds. To account for sportsbook hold or vig, adjust the implied probability upward so the true break-even win rate reflects the house share. For more on how vig affects payouts, see an explanation of vig.
For practical use, compute expected return per bet as (probability * payout) minus (1 - probability) times stake, then subtract fees and any per-bet transaction costs. Doing this arithmetic before placing stakes reveals whether a purportedly winning pick truly adds EV after costs.
A winning pick can reduce long-term returns when its expected value after fees and sportsbook hold is negative, when stake sizing increases volatility and risk of ruin, or when correlation concentrates portfolio risk.
Worked micro-example: suppose a bet returns 2.5 times the stake on a win (decimal odds 2.5), so the implied break-even without costs is 40 percent. If the sportsbook’s effective hold raises the required win rate by a few percentage points and you also pay small transaction fees, that same selection must clear a higher win-rate threshold to be profitable. This arithmetic shows how a winning longshot can still be negative EV once costs are applied U.S. SEC guidance on why fees matter.
When assessing individual picks, track both the raw win rate and the net return per dollar risked. The latter incorporates vig and transaction costs and directly maps to whether your bankroll will grow over repeated trials.
Position sizing and the Kelly perspective: when overbetting kills growth
The Kelly criterion in plain language
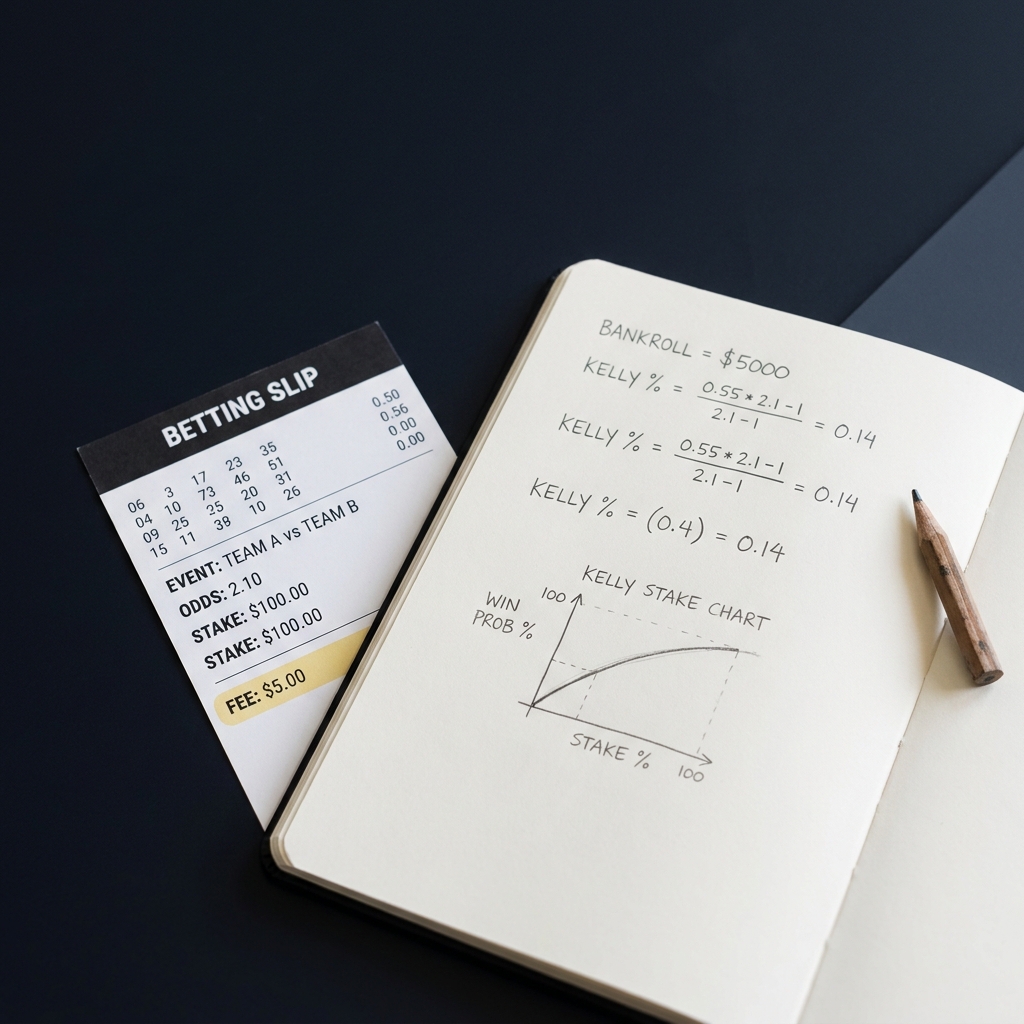
The Kelly criterion prescribes a stake size that maximizes the long-term growth rate of capital when you know the edge and the odds. It favors a balance: risking more when edge is clearer and pulling back when the edge is small or uncertain. The core principle is that you optimize growth, not the count of short-term wins Foundational work on the Kelly criterion.
Put simply, Kelly tells you to size bets so you do not overexpose the bankroll to volatility. Betting too large on a positive expectation increases variance and produces a volatility drag that reduces geometric growth, even if many individual bets win.
What happens when you over-size: volatility drag and risk of ruin
Overbetting amplifies drawdowns, and repeated large fractional bets can produce a high chance of temporary or permanent capital loss. Volatility drag is the tendency for variability in outcomes to shrink compound returns; large swings reduce the effective growth rate of a strategy and raise the probability of ruin.
Practical conservatism matters. Many experienced predictors use fractional Kelly, for example one-quarter or one-half Kelly, to limit volatility while still capturing positive edge. Scaling down from full Kelly reduces the risks of ruin and makes returns more stable, even if the count of short-term wins changes Foundational work on the Kelly criterion.

compute a fractional Kelly stake given probability, odds and bankroll
use fractional multiplier if risk averse
When you apply Kelly-derived sizing, compare the recommended fraction to your own risk tolerance and account rules. Many challenge platforms and funded-account models impose drawdown limits or max exposure rules; align your sizing with those constraints rather than chasing growth alone.
Another practical point: estimation error in your edge and probability inputs means full Kelly is often too aggressive. Even with a true positive edge, overconfidence in the input numbers produces stakes that expose you to sequences of losses that degrade long-run performance.
Portfolio context: correlation, diversification and drawdown effects
Why correlated picks increase portfolio volatility
Picks that are highly correlated move together, so clustering bets around the same team, market, or event type increases portfolio volatility and can worsen drawdowns. Diversification reduces the chance that a single outcome or event cluster destroys a large share of the bankroll FINRA guidance on diversification.
Correlation is especially material in sports prediction because many markets respond to the same signals: player injuries, weather, or a team’s form. If several picks share those drivers, a single development can flip multiple positions at once and produce a concentrated loss that offsets many prior wins.
At the portfolio level, checks matter more than isolated judgment calls. Build a simple correlation matrix for your common bet types or teams and set maximum exposure limits to any one market or correlated group. These limits can be absolute (max percent of bankroll at risk) or relative (max number of correlated positions simultaneously open).
Market structure and behavioral biases that make some wins deceptive
Sportsbook house hold and its implication for average bettors
Industry reporting shows sportsbooks retain a consistent house share on wagers, which means the average bettor faces negative expected value absent proven skill. That baseline house hold raises the bar for profitable strategies and explains why isolated winning tickets can still leave a bettor trailing on net returns American Gaming Association state of the states.
Because the market includes a built-in margin, a predictor must demonstrate a positive edge after the house share and any fees. Looking solely at hit rate ignores that the sportsbook’s structure systematically shifts the break-even point away from the bettor.
Favorite-longshot bias and why some longshot wins are traps
Behavioral research documents a favorite-longshot bias where longshots often offer worse expected value than their win probability implies. That pattern means occasional striking wins on longshots can mislead predictors into overvaluing a tactic that is negative EV overall Research on the favorite-longshot bias.
In practice, chase of longshot wins often produces a sequence of small losses punctuated by an exciting hit. Over time, the average return per dollar risked can be negative once the house take and fees are factored in. Being skeptical of hit-rate-only heuristics reduces the risk of mistaking luck for skill.
Worked scenarios: concrete examples where a winning pick hurts long-term P&L
Small-edge frequent bets with fees, and correlated parlays
Scenario 1, small-edge frequent bets. Start with the inputs you should capture: decimal odds, your estimated win probability, per-bet fees or effective sportsbook hold, stake size, and current bankroll. Compute expected return per bet as probability times payout minus the complementary loss amount, then subtract fees. Repeat over many trials to see how small negative EVs compound into noticeable drawdowns U.S. SEC guidance on fees. For a step-by-step EV walkthrough, see an expected-value betting guide.
Step 1: record decimal odds and convert to implied break-even. Step 2: insert your subjective win probability to compute edge. Step 3: subtract sportsbook hold and transaction costs to get net EV. Step 4: apply your chosen stake size and simulate several hundred repetitions or multiply EV by expected number of bets to estimate net contribution to P&L.
Result: even a stable hit rate can deliver negative aggregate returns if each bet’s net EV after fees is negative. Applying a fractional Kelly cap or reducing stake size until net EV per unit risk is positive helps prevent cumulative erosion.
Scenario 2, correlated parlays and same-team clusters. Parlays amplify odds but compound the house hold across legs; correlations across legs reduce the true diversification benefit and can increase the chance that related events cause simultaneous losses. A few parlay wins may look impressive, but over time the compounded hold and correlation make many parlay approaches worse than single-leg strategies American Gaming Association state of the states.
Step 1: list parlay legs and estimate their joint probability, being cautious about assuming independence. Step 2: compute parlay payout and implied joint break-even. Step 3: adjust for effective hold and any fees to get net EV. Step 4: compare parlay EV to the sum of single-leg EVs; often the parlay underperforms because of compounded costs and correlated outcomes.
Applied change: cap parlay exposure, limit number of same-team legs, or avoid correlated legs entirely to protect portfolio EV. If you see parlay wins but overall net returns stagnate or decline, re-check the joint probability assumptions and the per-leg hold impact Research on the favorite-longshot bias.
Try the EV-and-sizing worksheet inspired by the FundedPlays Challenges description
Download a simple EV-and-sizing worksheet to test whether your typical picks clear fees and fit a Kelly-informed stake size.
How fractional Kelly or capping exposure changes outcomes. Re-run the scenario inputs with fractional Kelly stakes and compare resulting compound growth estimates. Often a lower fraction reduces volatility enough that the long-run geometric growth rate improves even if short-run wins are fewer.
Checklist of inputs for readers to model their own strategy: decimal odds, subjective win probability, sportsbook hold estimate, per-bet fees, stake size rule, bankroll, and simple correlation estimates for common bet clusters. Capture these consistently to avoid confusing anecdotal wins with sustainable edge. See our blog for related posts.
Common mistakes, checklist and practical rules to avoid turning wins into losses
Top errors predictors make
Common errors include: ignoring fees and hold, over-sizing stakes relative to edge, clustering correlated bets without limits, chasing longshots after a hit, failing to track net returns, and lacking clear rules for scaling after streaks.
Each of these mistakes links directly back to the mechanics described earlier: fees eat EV, overbetting multiplies volatility drag, correlation increases drawdown, and longshot bias can turn exciting wins into systemic losses.
Before you place a pick, run through this gate checklist in order. 1) Does the selection have positive EV after subtracting sportsbook hold and fees? 2) Is the recommended stake under your max fraction of bankroll or the fractional Kelly cap? 3) Does the pick add to correlated exposure above your pre-set limit? 4) Will you track net return and revisit the model on a regular cadence? 5) Is this pick consistent with challenge or account drawdown rules? 6) If you are tempted by a longshot, confirm the expected value calculation explicitly.
Use short, imperative entries and record outcomes. Consistent record keeping turns anecdote into evidence and helps you separate true edge from lucky streaks Kelly criterion guidance.
Conclusion: how to judge a pick for long-term contribution
Short summary of the key decision criteria
Decide on picks by asking three core questions: does the pick offer positive expected value after fees and hold, is the stake consistent with a Kelly-informed sizing cap, and does the pick keep portfolio correlation within limits. Prioritize net returns and drawdown control over hit rate alone. (Learn more at Funded Plays.)

Next steps and mindset: track net returns, model scenarios with honest estimates of fees and correlation, and iterate. Treat each pick as a contribution to a measured, repeatable process rather than a standalone contest. Platforms that emphasize structured evaluation and funded account progression can help predictors test sizing and discipline under rules designed for long-run assessment (see how Funded Plays evaluations work), but success depends on consistent measurement and rule-based behavior.
Final takeaway: a winning pick that does not clear expected value after costs or that increases portfolio risk can be worse than a losing pick that preserves capital and reduces volatility. Make decisions that cumulatively raise net returns and protect against ruin rather than chasing headline wins.
Expected value measures average return per dollar risked over time and includes odds and costs; win rate only counts how often bets win and can be misleading if payouts and fees are not considered.
Fractional Kelly scales down the full Kelly stake to reduce volatility and risk of ruin while preserving some long-run growth benefits.
Yes, because longshots often suffer from favorite-longshot bias and can be negative expected value after accounting for sportsbook hold and fees.
References
- https://www.investor.gov/introduction-investing/investing-basics/why-fees-matter
- https://link.springer.com/book/10.1007/978-981-4383-50-6
- https://www.finra.org/investors/insights/diversification
- https://www.americangaming.org/resources/state-of-the-states/
- https://www.aeaweb.org/articles?id=10.1257/mic.2.2.190
- https://www.fundedplays.com/challenges
- https://www.rebelbetting.com/en-us/valuebetting/expected-value
- https://www.pinnacleoddsdropper.com/blog/what-is-vig
- https://oddsindex.com/guides/expected-value-betting-guide
- https://www.fundedplays.com
- https://www.fundedplays.com/blogs
- https://www.fundedplays.com/blogs/how-fundedplays-evaluations-work