
What we mean by separating leisure spending and financial expectations
Define entertainment as a distinct budget category
Separating Entertainment from Financial Expectations begins with a simple idea: label leisure spending so it does not mix with essentials. The U.S. Bureau of Labor Statistics treats entertainment as its own household spending category, which supports treating leisure outlays as discretionary rather than mandatory for most budgets, and that distinction helps when allocating limited dollars. BLS Consumer Expenditure Survey
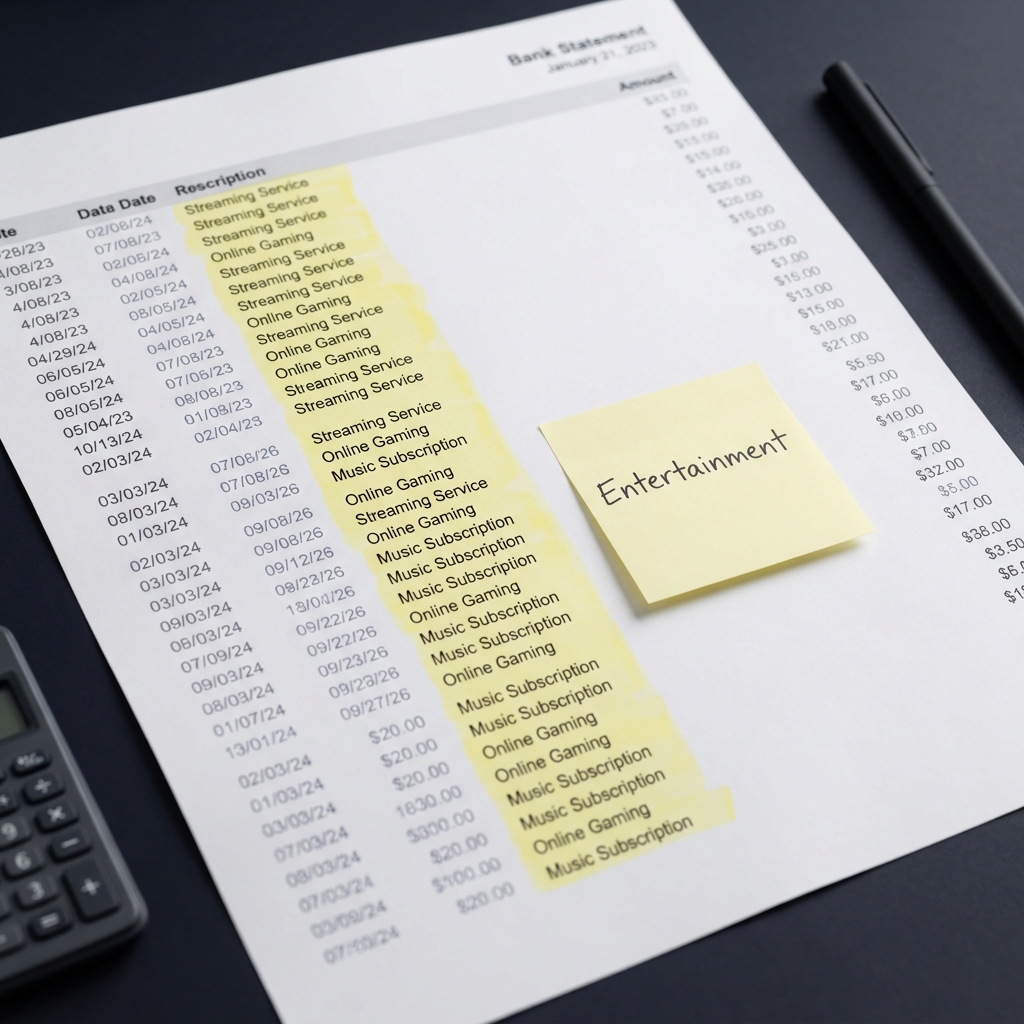
In practical terms, a labeled entertainment line item can include movie nights, streaming subscriptions, paid sports prediction entries, event tickets, and casual in‑app purchases. When these items sit in a single, named category in a written or digital budget, it becomes easier to track how they interact with essentials like housing and food. Federal consumer guidance recommends catalogs and written budgets that separate needs from wants so households can monitor recurring charges and avoid surprises.
Why clarity matters: needs versus wants
Making a clear distinction between needs and wants reduces decision friction at the point of purchase. For example, knowing that a streaming subscription comes from an earmarked entertainment allowance means a replacement subscription does not quietly erode an emergency cushion. A short, labeled example helps: if your monthly essentials and savings require 80 percent of income, the remaining discretionary 20 percent can be carved into entertainment, dining, and hobbies, with each suballocation tracked separately.
A written or digital budget that notes recurring entertainment charges is more effective than an informal rule of thumb because it creates a documented reference when choices compete. The Federal Trade Commission advises using a written budget and tracking recurring charges to avoid overspending, which is a useful practice for anyone seeking to protect financial goals while still enjoying leisure activities. FTC budgeting guidance
By treating entertainment as a separate, earmarked category in a written or digital budget, using precommitment tactics like caps and cooling-off periods, and auditing recurring charges regularly, you can preserve enjoyment while protecting savings and essential expenses.
Why the distinction matters now: financial stress, subscriptions, and small leaks
What household stress data show
Economic surveys show many adults report financial strain, and that reality raises the stakes for discretionary spending choices. The Federal Reserve's 2024 household survey highlights persistent pockets of stress that make clear spending boundaries more valuable for people trying to meet savings goals and handle unexpected costs. When stress is common, a disciplined allocation for entertainment helps prevent small indulgences from cascading into shortfalls. Federal Reserve SHED
When household money is tight, recurring entertainment charges that feel small on their own can accumulate into meaningful monthly leakage. Subscriptions, microtransactions, and automatic renewals are structured to be low‑friction, and that convenience is exactly what makes them easy to overlook. Recognizing recurring charges and grouping them under an entertainment subaccount makes it possible to see the aggregate effect rather than only individual line items.
How recurring entertainment charges accumulate
Consider a brief micro-scenario: a single person who values variety keeps four streaming services, a couple of niche apps, and occasional in‑app purchases. Each renewal is small and psychologically easy to accept, but together they can equal the cost of a meaningful savings contribution. A formal separation of entertainment spending-tracking and auditing those charges-creates visibility and reduces the chance that small, repeated payments undermine long‑term objectives.
For many households the choice is not between entertainment or nothing, but between keeping enjoyment and improving resilience. With clear limits and periodic audits, you can preserve favored services while protecting core financial goals. The Bureau of Labor Statistics’ categorization of entertainment supports treating these outlays as discretionary for budget decision making. BLS Consumer Expenditure Survey
A practical framework to separate entertainment from financial expectations
Step 1: identify and quantify entertainment outlays
Begin by listing every entertainment cost you can think of for the last one to three months: subscriptions, pay‑per‑view charges, tickets, platform fees, and hobby expenses. The goal is to convert vague impressions into concrete amounts so you can see the total. Start wide and then prune: you may discover services you no longer use or features that duplicate others.
Step 2: create earmarked subaccounts or line items
Mental accounting supports earmarking. By assigning a fixed amount to a labeled subaccount for entertainment, you reduce the temptation to borrow from savings or essentials. Opening a dedicated subaccount, using a budgeting app’s tag feature, or creating a labeled savings bucket achieves the same practical separation. Behavioral research on mental accounting shows that purpose‑specific funds help people stick to intended spending limits. Mental Accounting Matters

CTA>Try a seven‑day subscription scan using the steps below to see which small recurring costs add up in real life.
Step 1 checklist: find recurring charges on bank and card statements, export or screenshot a month of transactions, and flag items that fit in entertainment. See Making a Budget.
Step 2 checklist: assign each flagged item to an earmarked line labeled "Entertainment" and total the monthly impact. If you use a virtual or labeled subaccount, note the current balance and set a monthly deposit amount.
Step 3: set caps, rules, and review cadence
Set a concrete cap for your entertainment subaccount and document it. A cap is simply a rule you write down: for example, "Total entertainment budget is X per month." Combine the cap with rules such as a cooling‑off period for nonrecurring purchases and a one‑in, one‑out rule for new subscriptions. Those precommitment tactics help counter impulse and loss‑chasing behaviors.
How to decide the right limits: criteria and trade-offs
Priorities-based decision rules
Good limits begin with objective checks: ensure essentials are covered, maintain at least a modest emergency cushion, and confirm steady progress toward savings goals before setting discretionary caps. One useful rule is to complete essentials and a minimum savings contribution before allocating money to entertainment to avoid shortfalls later.
Documenting the rationale for each cap helps when emotions push for exceptions. If you decide an exception is reasonable, record why, how much, and when you will return to the original cap. That simple documentation makes future adjustments deliberate rather than reactive and helps keep entertainment spending aligned with broader priorities. The SEC's guidance on creating and using a budget outlines similar steps for prioritizing funds and tracking performance. SEC budgeting roadmap
When to be flexible and when to tighten limits
Flexibility is practical for one-time events or special occasions, but frequent exceptions erode discipline. Use a written rule for one-off events: for instance, permit one treated outing per quarter funded from a temporary buffer rather than the baseline entertainment cap. If exceptions become common, tighten the cap and increase the review frequency until discipline returns.
Trade-offs sometimes favor short‑term enjoyment; the key is to make those trade-offs visible and reversible. If a household chooses to spend more on a single event, adjust the next month’s entertainment deposit to compensate. Keeping the decision documented prevents creeping erosion of savings or emergency cushions and keeps control grounded in measurable steps.
Practical tools and tactics: from subscription audits to cooling off
Performing a subscription audit
A subscription audit is methodical: gather bank and card statements for the last three months, list every recurring charge, note renewal dates and prices, and estimate average monthly cost. Then ask two questions for each item: do I use it regularly, and does it provide value relative to alternatives? That simple rubric makes the decision process efficient. See Voya's subscription audit.
Practical tactics include setting calendar reminders for upcoming renewals, consolidating duplicate services, and scheduling a quarterly audit so that low‑value subscriptions are easier to cancel. For practical how-to, see our blog and Meriwest's guide. Federal consumer guidance recommends tracking recurring charges, which makes regular audits a standard part of a written spending plan. FTC budgeting guidance

Using automated alerts and subaccount rules
Automated alerts from banks or budgeting apps, transaction labels, and automatic transfers into a labeled subaccount reduce guesswork and make discipline easier. For example, an automatic transfer to a labeled entertainment subaccount on payday enforces the precommitment that mental accounting supports, and alerts for any transaction above a threshold act as a cooling‑off prompt before impulse purchases.
Cooling‑off rules are simple to implement: require a 48‑hour wait for nonrecurring entertainment purchases above a set dollar amount, or limit impulse buys to a small, preapproved monthly allowance. These precommitment strategies help reduce present bias by inserting friction at the moment choices are made.
Behavioral pitfalls and corrective habits
Loss aversion and present bias in entertainment spending
Loss aversion and present bias can cause people to chase losses or prioritize immediate pleasure over long‑term goals. When a small entertainment expense is framed as recouping past spending or as a low‑cost immediate reward, it becomes harder to stick to a written cap. Summarizing foundational decision theory can help explain personal patterns and reduce self‑blame when choices go off plan. Prospect Theory paper
One simple corrective habit is a default rule that requires funds to be available in the entertainment subaccount before discretionary spending. If the fund is empty, the rule prevents additional entertainment purchases until the next funding cycle. This default creates natural resistance to loss‑chasing and leverages mental accounting in favor of the long term.
Habits that protect long-term plans
Routine protections include monthly reconciliation, calendar-triggered audits, and a one‑in, one‑out policy for new subscriptions. Over time, these habits reduce leakage and make the entertainment budget predictable. Pairing precommitment rules with easy, repeatable actions tends to outperform ad hoc restraint.
Anchoring habits to existing routines, such as reconciling subscriptions while paying monthly bills, makes the process less onerous. Habitual checks also create a record of decisions that can be reviewed during quarterly planning, making it easier to defend successful choices and correct course when necessary. Behavioral studies show that combining precommitment with earmarked funds improves adherence. Mental Accounting Matters
Real-world scenarios: examples that keep enjoyment without derailing goals
Single-person example with multiple subscriptions
Scenario: a single person enjoys multiple niche streaming services and gaming subscriptions. They perform a subscription audit, list four active services, and tag each one in their budgeting tool. The audit reveals overlapping content and identifies one low‑value subscription to pause for the next quarter. The person moves the saved amount into an earmarked entertainment subaccount and sets a monthly cap to prevent reversion.
The steps taken are straightforward: audit, tag, pause or cancel low-value items, and set a cap. The review cadence is monthly for subscriptions and quarterly for discretionary event spending. Evaluating success looks like fewer unexpected renewals and a stable earmarked balance that funds occasional extras. Read more at this post.
step-by-step subscription audit and subaccount setup
Use with bank statements and app transaction lists
Household example balancing events and savings
Scenario: a two‑person household wants to maintain savings targets while enjoying occasional live events. They calculate essentials and a minimum savings contribution first, then allocate a monthly entertainment deposit to an earmarked subaccount. For larger events, they create an event buffer that draws from a portion of future monthly entertainment deposits rather than from emergency savings.
The household documents trade-offs: if they spend more on a concert month, they reduce the next month’s entertainment deposit until the average returns to the cap. This recorded rationale prevents creeping adjustments and keeps the emergency cushion intact. Success is measured qualitatively by reduced friction at renewal time and quantitatively by consistent savings contributions and a predictable entertainment balance. The mental accounting approach supports predictable allocations that protect resilience. Mental Accounting Matters
Closing: an action checklist and next steps
30-day starter checklist
30-day starter checklist: 1) gather three months of statements and identify recurring entertainment charges; 2) total those charges and create an earmarked entertainment line or subaccount; 3) set a temporary monthly cap for entertainment; 4) implement one cooling‑off rule for impulse purchases; and 5) schedule a 30‑day review and a quarterly audit. These actions follow federal guidance to use a written budget and track recurring charges. FTC budgeting guidance
When to seek more help
If basic budgeting steps do not restore confidence, or if unexpected debts or income volatility complicate decisions, it can help to consult a financial counselor who can review priorities and recommend a tailored plan. For most people, starting with a short subscription audit and an earmarked entertainment account produces clarity and restores control.
Keeping entertainment separate from financial expectations is not about eliminating pleasure; it is about choosing when and how to enjoy leisure without surprising consequences. A simple, documented plan preserves enjoyment while protecting what matters most. Learn more at Funded Plays.
Perform a quick subscription check monthly and a thorough audit quarterly to catch renewals and low-value services.
No. Mental accounting is a practical tool that helps earmark funds and enforce discipline, making spending decisions clearer and more intentional.
Yes. Prioritize essentials and a minimum savings contribution first, then allocate a modest entertainment cap from remaining discretionary funds.
References
- https://www.bls.gov/news.release/cesan.nr0.htm
- https://consumer.ftc.gov/articles/budgeting
- https://www.federalreserve.gov/consumerscommunities/shed.htm
- https://doi.org/10.1002/(SICI)1099-0771(199909)12:3<183::AID-BDM318>3.0.CO;2-F
- https://www.fundedplays.com/challenges
- https://doi.org/10.2307/1914185
- https://www.investor.gov/introduction-investing/investing-basics/roadmap-saving-and-investing/creating-and-using-budget
- https://www.fundedplays.com
- https://www.fundedplays.com/blogs
- https://www.fundedplays.com/blogs/how-fundedplays-evaluations-work
- https://consumer.gov/your-money/making-budget
- https://www.voya.com/individuals/learn/subscription-audit-four-steps-to-find-more-money-your-budget
- https://www.meriwest.com/our-story/blog/subscription-trap-how-audit-cut-and-optimize-your-monthly-services