What 'legally bet on sports online' means for your taxes
If you legally bet on sports online, your winnings are taxable for federal purposes and must be reported on your individual income tax return, even when no paper form is issued.
For federal tax treatment and reporting basics, the Internal Revenue Service treats online wagering the same as in-person gambling, so proceeds from online sports betting are reportable income under IRS guidance Topic No. 419, Gambling Income and Losses.
Check your challenge and platform records
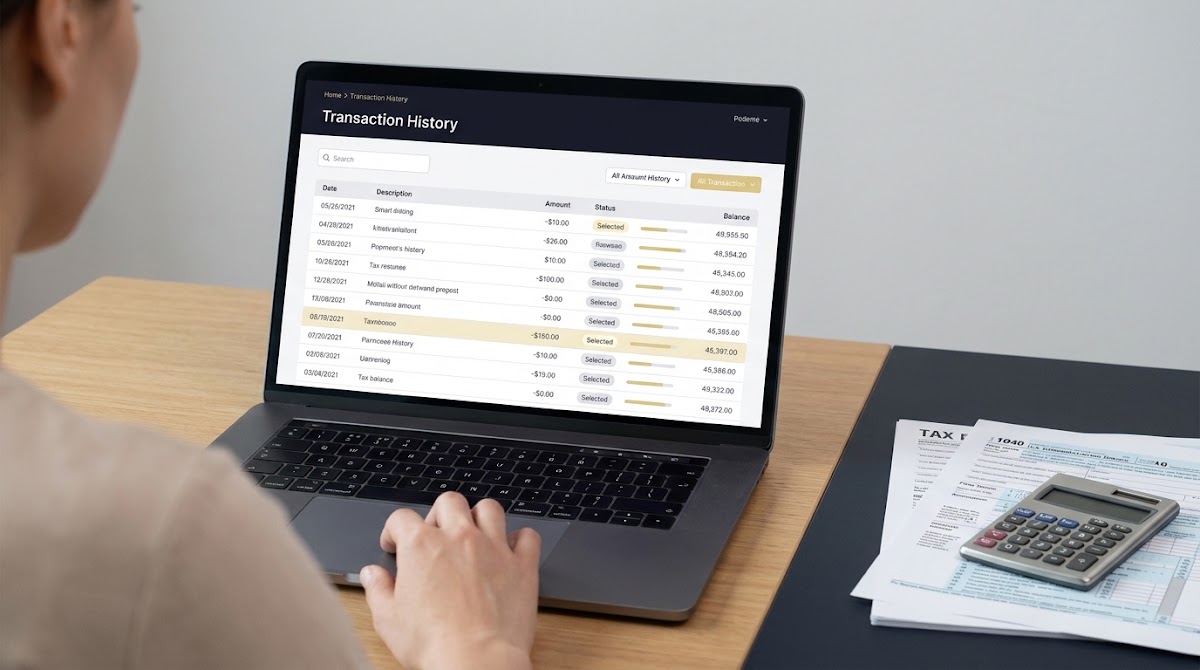
Check your transaction history and save receipts before you file so you can accurately report winnings and losses.
Put simply, the fact that a bet happened online does not create a tax exemption or special rule. The IRS guidance is explicit that gambling winnings are taxable and must be included on your return, and that obligation applies whether the activity took place on a website, an app, or in person Topic No. 419, Gambling Income and Losses.
That means you should track gross winnings, the dates of events, and any records the platform provides. Keeping clear records helps you meet reporting requirements even if no Form W-2G is issued.
Federal tax status of gambling winnings
At the federal level, all gambling winnings are reportable miscellaneous income and must be included in taxable income for the year they are received, according to the Form 1040 instructions 2025 Instructions for Form 1040 and 1040-SR.
Reportable amounts include winnings from sports betting, fantasy contests that are not legally exempt, casino games, and other wagering proceeds. The IRS guidance applies uniformly, so report gross winnings and reconcile any withholding or Forms W-2G that were issued.
Why online betting is treated the same as in-person wagering
Online and in-person wagers are treated the same because the tax rules focus on the nature of the income, not the platform where it was earned. The IRS clarifies that the source is gambling income and must be reported regardless of format Topic No. 419, Gambling Income and Losses.
As a practical matter, many online platforms provide digital statements, transaction logs, or tax documents that you can save to substantiate amounts when reporting on your federal return.
Who must report sports betting winnings and where to put them on your tax return
All individuals who receive gambling winnings must report those amounts on their federal tax return, even if a Form W-2G is not issued by the payer.
Per the Form 1040 instructions, gambling income is reported as Other Income on Schedule 1 and then included on the Form 1040 total income line, so you should plan to include your net results for the year when you file 2025 Instructions for Form 1040 and 1040-SR.
Where to enter amounts: list gross winnings on Schedule 1 as other income, and include the total on Form 1040. Do not net winnings and losses on the income line; losses are handled separately when you itemize deductions.
Keep in mind that a platform-issued Form W-2G reports certain winnings to the IRS, but not receiving a W-2G does not eliminate your reporting obligation. You must still report income you received even when no form arrives Topic No. 419, Gambling Income and Losses.
Your records should include dates, amounts won, copies of any Forms W-2G, and platform statements. These items support the figures you enter on Schedule 1 and, if applicable, Schedule A when claiming losses.
How winnings feed into Form 1040 and Schedule 1
On Form 1040, report gambling winnings through Schedule 1 under other income, then carry the total to Form 1040. If a payer issued a W-2G showing federal income tax withheld, that withholding is included on your return as federal income tax paid.
When reconciling your return, list gross winnings separately from any amounts withheld so you can calculate total tax owed or refund due after credits and withholding are considered 2025 Instructions for Form 1040 and 1040-SR.
When you might receive a W-2G and what it means for your return
Payers issue Form W-2G in specific situations where reporting thresholds are met, and that form reports the amount to both you and the IRS; issuance is a reporting trigger, not a tax-free threshold exception Instructions for Forms W-2G and 5754. About Form W-2G
If you receive a W-2G, the amount shown should be entered on your return and any federal tax withheld shown on the form should be claimed as tax paid. If you do not receive a W-2G, you are still required to report your winnings and keep records to substantiate them.
When payers must issue Form W-2G and when withholding applies
Payers must issue Form W-2G when specified thresholds are met, such as certain large wins or specific prize types, and those thresholds help platforms and payers know when to report or withhold Instructions for Forms W-2G and 5754. See Internal Revenue Bulletin 2026-19.
Common thresholds include $1,200 or more for slot machines or bingo, $1,500 or more for keno, $5,000 or more net for poker tournaments, and $600 or more that is at least 300 times the wager for other wagering; these are reporting and withholding triggers and not exemptions from tax Instructions for Forms W-2G and 5754. Form W-2G (PDF)
When a payer issues a W-2G, it may also show federal income tax withheld at the statutory rate for certain prizes, which you then reconcile on your Form 1040. A W-2G helps both you and the IRS track reportable winnings.
Platforms and payers use these thresholds to determine when to report to the IRS. If the payout does not reach a threshold, a platform might not send a W-2G, but the income remains reportable and taxable under federal rules Topic No. 419, Gambling Income and Losses.
Common W-2G thresholds and examples
A typical example: a large tournament prize that meets the poker threshold will generate a W-2G and may have federal withholding shown. Smaller recurring winnings, even if frequent, may not each trigger a W-2G but still need to be totaled and reported.
Use platform statements to aggregate amounts for the year and compare them to any W-2G forms you receive. If you find a discrepancy, contact the payer for clarification and retain records of your inquiries.
The 24% withholding rule and backup withholding basics
Certain reportable gambling winnings are subject to 24 percent federal income tax withholding and, if a taxpayer identification number is not provided, backup withholding rules can also apply, which means withholding can affect your take-home amount Instructions for Forms W-2G and 5754.
Withholding is a prepayment of tax. If too much tax is withheld, you may receive a refund after you file. If too little is withheld, you may owe additional tax and potentially penalties unless you make estimated payments.
How gambling losses and itemized deductions work
You can deduct gambling losses only up to the amount of your gambling winnings, and only if you itemize deductions on Schedule A; you cannot claim a net wagering loss for federal tax purposes under the statute limiting such deductions 26 U.S.C. §165(d).
In practice, that means you list all winnings as income, and if you itemize, report losses on Schedule A up to the amount of those winnings. You cannot use losses to create a deduction larger than your winnings.
When you can deduct gambling losses
Only taxpayers who itemize deductions may deduct gambling losses, and the deduction cannot exceed reported winnings. If you take the standard deduction, gambling losses are not separately deductible.
To claim losses, document each loss with records such as tickets, receipts, or platform transaction histories. These records support the deduction and help if the IRS requests substantiation Topic No. 419, Gambling Income and Losses.
Limits under U.S. tax law
The statutory rule prevents taxpayers from deducting a net wagering loss as an ordinary loss for federal income tax purposes. That is, you cannot offset other income with gambling losses beyond your winnings, which preserves the reporting of gross income from gambling and limits deductions to documented losses up to that amount 26 U.S.C. §165(d).
Economically, this means if you had $10,000 in winnings and $12,000 in losses, you could deduct only $10,000 of losses on Schedule A if you itemize. You would still report the $10,000 in winnings on your income lines.
Estimated tax, withholding adjustments, and avoiding penalties
If withholding from winnings is insufficient to cover your tax liability, you may need to make estimated tax payments or increase withholding elsewhere to avoid an underpayment penalty; IRS Publication 505 explains these obligations and methods to comply Publication 505.
Withholding at 24 percent on certain reportable winnings reduces immediate tax due, but it may not cover your full tax liability depending on your overall income. Use withholding or quarterly estimated payments to manage the gap.
Track annual gambling winnings, losses, and withholding in one place
Keep digital copies of records
Start by estimating your annual net tax exposure from gambling activity and other income sources. If projections show a balance due, either increase withholding from other wages or make quarterly estimated payments to reduce penalty risk.
Publication 505 guides when estimated payments are required and offers safe-harbor rules based on prior-year tax to avoid penalties when you expect taxable amounts not covered by withholding Publication 505.
When to make estimated tax payments
If you expect to owe tax of a certain size after withholding and credits, you may be required to pay estimated taxes quarterly. This is common for people with sizable gambling income that did not have sufficient withholding during the year.
Track your wins, losses, and any withholding shown on W-2G forms or platform statements so you can calculate estimated payments and adjust as the year progresses.
How to adjust withholding to avoid underpayment penalties
You can adjust tax withholding on other income sources by submitting a revised Form W-4 to an employer or by making quarterly estimated payments if withholding cannot be increased, thereby smoothing tax liability throughout the year.
Practical steps: maintain a running tally, set calendar reminders for quarterly payments, and consult Publication 505 for methods to calculate safe-harbor amounts and reduce penalty risk Publication 505.
Common mistakes and audit red flags to avoid
A few recurring errors raise audit risk: failing to report winnings because you did not receive a W-2G, overstating losses, missing documentation, or ignoring withholding and estimated tax rules.
Failing to report income because you did not get a W-2G is common but incorrect; the absence of that form does not change the underlying requirement to report gambling winnings Topic No. 419, Gambling Income and Losses.
Frequent filing errors
Other frequent mistakes include claiming losses without proper documentation, mixing personal and gambling bank records, and not reconciling platform statements against your reported amounts. These issues make audits more difficult to resolve.
To reduce errors, keep a clear folder of records for each event or session, and reconcile totals periodically rather than waiting until tax time. Accurate books reduce the chance of mistakes that draw IRS attention.
Recordkeeping and documentation pitfalls
Documentation that helps: screenshots of digital payouts, platform transaction histories, copies of any W-2G forms, and notes that explain how totals were calculated. Missing or inconsistent records are a frequent problem in examinations.
Do not attempt to net across unrelated years or offset non-gambling income with gambling losses in a way that contradicts the statutory limitation under tax law 26 U.S.C. §165(d).
Practical reporting scenarios: 5 examples and how to handle them
1) Small regular wins with no W-2G. If you collect small, frequent winnings that never trigger a W-2G, total the gross amounts for the year from platform statements and report that total as other income on Schedule 1.
2) A single large win with a W-2G and withholding. When you receive a W-2G showing a large payout and federal withholding, report the full winning amount on Schedule 1 and claim the withholding as tax paid on Form 1040.
Under current U.S. federal law, there is no amount you can win from online gambling that is automatically tax free. All gambling winnings are taxable and must be reported on your individual federal tax return; withholding and W-2G thresholds affect reporting and tax paid but do not create a tax-free allowance.
3) Poker tournament net prize reporting. For poker tournaments that meet the net prize threshold and generate a W-2G, include the net prize as reportable income and reconcile any withholding shown on the form when you file.
4) Year with more losses than wins. If your documented losses exceed winnings, you may only deduct losses up to the amount of your reported winnings on Schedule A if you itemize; you cannot deduct an excess loss against other income.
5) Multiple platform statements and aggregating records. When you use multiple platforms, aggregate gross winnings from all statements and compare them to any W-2G forms you received. Reporting the combined total ensures you meet the federal reporting requirement Topic No. 419, Gambling Income and Losses.
In each scenario, keep the transaction-level records that support your totals and retain copies of any W-2G forms as part of your year-end file. If withholding was taken, use that as a credit when computing final tax due on Form 1040 2025 Instructions for Form 1040 and 1040-SR.
State taxes and next steps (why state rules may differ)
State tax treatment of gambling winnings varies by state, so you should check your home state tax authority for specific rules and filing requirements; federal rules do not replace state obligations.
Some states conform closely to federal treatment, while others have different thresholds or exemptions. If you have state tax questions, review your state department of revenue guidance or consult a tax professional for personalized advice.
As a practical matter, keep the same records for both federal and state reporting: platform statements, transaction logs, Form W-2G copies, and notes explaining your calculations. That reduces confusion during multi-jurisdictional filings. For more background, see the Funded Plays blog on evaluations.
Key takeaways and responsible next steps
Quick checklist: report all winnings on your federal return, keep detailed records, claim losses only if you itemize and only up to the amount of winnings, and monitor withholding and estimated tax obligations to avoid penalties. Visit the Funded Plays homepage for related resources.
When to seek professional help: consult a tax professional if you have complex multi-state issues, large volumes of transactions, inconsistent platform reporting, or questions about how withholding and estimated payments affect your overall tax picture, or visit the Funded Plays blog.
Authoritative federal sources to consult: IRS Topic No. 419 for gambling income guidance and the Form 1040 instructions for reporting specifics Topic No. 419, Gambling Income and Losses.
Yes. Even without a W-2G you must report all gambling winnings on your federal return and keep records that substantiate the amounts.
You can deduct gambling losses only if you itemize and only up to the amount of your gambling winnings; you cannot claim a net wagering loss beyond winnings.
Some reportable winnings are subject to 24 percent federal withholding, but not all wins will have withholding; you may need to make estimated payments or adjust other withholding.
References
- https://www.irs.gov/taxtopics/tc419
- https://www.irs.gov/instructions/i1040
- https://www.irs.gov/instructions/iw2g
- https://uscode.house.gov/view.xhtml?req=granuleid:USC-prelim-title26-section165&num=0&edition=prelim
- https://www.irs.gov/publications/p505
- https://www.fundedplays.com/challenges
- https://www.irs.gov/forms-pubs/about-form-w-2-g
- https://www.irs.gov/pub/irs-pdf/fw2g.pdf
- https://www.irs.gov/irb/2026-19_IRB
- https://www.fundedplays.com
- https://www.fundedplays.com/blogs
- https://www.fundedplays.com/blogs/how-fundedplays-evaluations-work