
What drawdown means and why weekly and monthly limits matter
Definition: peak, trough, and peak-to-valley drawdown
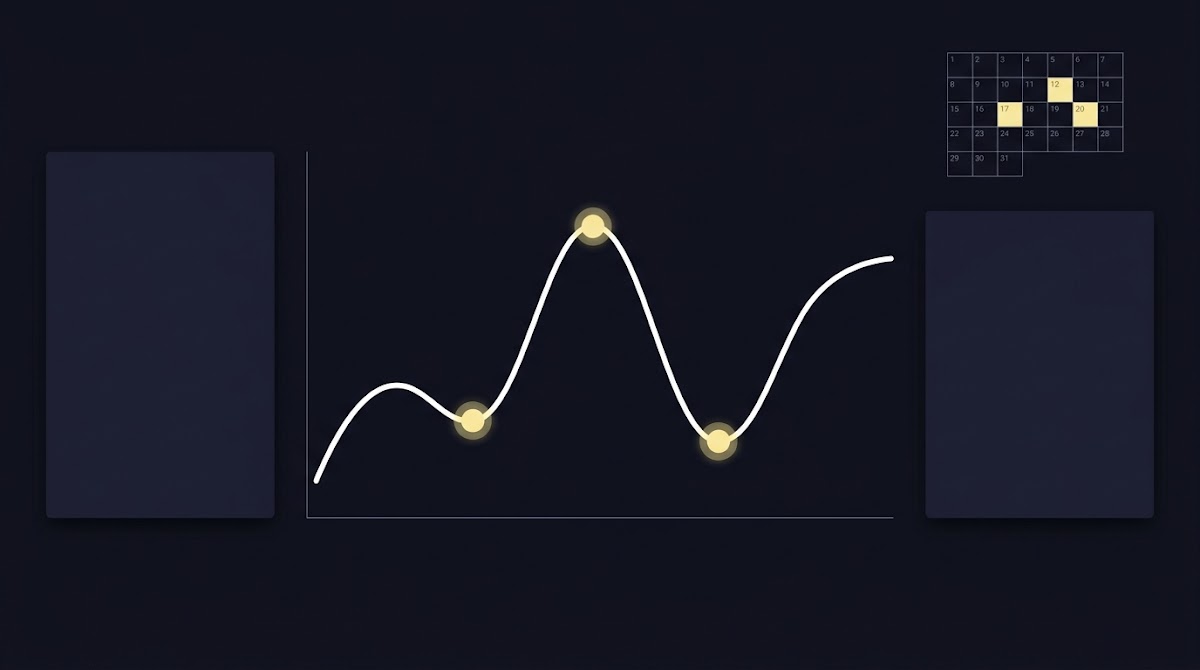
Drawdown describes the decline from a peak value to a subsequent trough in an account, measuring how much equity falls before a recovery. The U.S. regulatory definition frames drawdown as losses from a peak over a period and uses the worst peak-to-valley drawdown to show the maximum cumulative decline within that span, which helps standardize how declines are reported and compared eCFR definitions.
The common calculation for maximum drawdown uses the peak and trough values to express decline as a percent: (trough value minus peak value) divided by peak value, usually reported as a negative percent or an absolute percent showing the depth of the fall. This formula is the standard way practitioners and educators explain the magnitude of downside moves Investopedia definition.
Define clear measurement windows and a baseline, pick percentage and monetary caps that reflect strategy volatility, map caps to explicit stop or scale-down actions, automate enforcement if possible, and review results regularly to recalibrate.
Why controlling drawdown matters for disciplined forecasting
Setting weekly and monthly limits helps forecast-focused participants keep short-term losses from eroding long-term edge, because fixed-horizon caps force pauses or scale-backs before a small loss becomes a large equity decline. Responsible-play guidance encourages personal monetary limits and pauses when limits are reached as a consumer protection practice Safer Sports Betting guidance.
Regulatory and program tools that promote voluntary limit-setting make pre-commitment familiar to many users, so applying weekly and monthly drawdown rules fits into a broader trend of using time-based and monetary controls to protect participants and preserve disciplined behavior PlayMyWay program.
How to Set Weekly and Monthly Drawdown Limits: a step-by-step framework
Step 1: pick a horizon and define the measurement window
Begin by choosing whether you need a weekly drawdown limit, a monthly drawdown rule, or both. A weekly drawdown limit monitors performance inside calendar or rolling seven-day windows, while a monthly drawdown rule covers the longer month window and captures larger swings. Call out which windows you will use and make them explicit in writing before you trade or predict.
Be clear whether the window is calendar-based (Monday to Sunday, or 1st to last day of month) or rolling (prior seven or 30 days). Using a consistent measurement window prevents confusion when assessing whether a trigger has occurred. If you are adapting practices used in regulated contexts, document the same measurement window in your rules so comparisons and records are consistent with technical standards.
Step 2: choose the baseline - starting balance or intra-period peak
Decide whether your cap will reference the starting balance for the period or the highest intra-period peak. Using the starting balance is simple: the cap is a percentage of the balance you begin the week or month with. The intra-period peak method measures drawdown against the highest equity reached inside the window, which captures peak-to-valley declines more precisely eCFR definitions.
Document the baseline choice and how you will record peaks and troughs. If you plan to use intra-period peaks, specify how often you sample equity and whether you use end-of-day snapshots or real-time values to avoid ambiguity when a trigger approaches.
Configure limits on the Funded Plays Challenges page and document your rules
Set an initial percentage and a monetary cap now, then follow the next steps to map that cap to a clear stop or scale-down action.
Step 3: set a percentage cap and a monetary cap
Pick a percentage cap that reflects how much downside you are willing to accept in the window, and convert that percentage into a monetary stop using your baseline. For example, multiply the starting balance by the percentage cap to get a loss amount that becomes your monetary stop. This conversion makes the rule actionable and removes subjective judgment when the limit is reached Maximum drawdown formula.
When choosing the percent, consider strategy volatility and typical variance. A more volatile approach needs a wider percent to avoid frequent false triggers. Add a small buffer when appropriate so ordinary variance does not produce repeated pauses that erode discipline and learning.
Step 4: map the cap to stop or scale-down actions
Translate the cap into precise actions: stop all activity for the remainder of the window, reduce stake sizes by a set factor, or move to observation-only mode until a cooling-off period ends. The action should be enforceable and written as a rule everyone using the account follows, such as "If weekly drawdown limit hits X percent, pause for Y hours or until the next window begins."
Where platforms allow, automate the action with limits or time-outs. Using pre-commitment tools reduces the risk of emotional overrides and aligns practice with regulator-endorsed controls for consumer protection Remote gambling technical standards.

Choosing the baseline: starting balance versus intra-period peak
Pros and cons of using starting balance
Using the starting balance keeps the math simple and is easy to communicate: the cap is a percent of the amount you began the week or month with. This approach is easy to audit and avoids disputes about sampling frequency, making it useful for beginners and for short, clearly bounded challenges.
However, starting-balance baselines can understate risk when equity climbs early in a window and then falls sharply. In that case, a starting-balance cap will not reflect the real peak-to-valley loss that happened after the climb, which may leave a gap in downside protection.
Pros and cons of using intra-period peak
Measuring drawdown against the intra-period peak aligns closely with the worst peak-to-valley drawdown concept used in regulatory texts, because it references the highest value reached and therefore captures the largest observed decline inside the window eCFR definitions.
The trade-off is that peak-based methods require clear sampling rules and slightly more bookkeeping. You must define how often you record equity peaks, whether you use real-time values or end-of-day snapshots, and how brief equity spikes are handled when they would meaningfully change the cap.

When to prefer one approach over the other
Choose starting-balance caps when you need simplicity and low administrative overhead, such as for short evaluation runs or when learning a new strategy. Choose an intra-period peak when protecting gains and when you expect intra-window runs that could expose you to larger peak-to-valley losses. (learn about Funded Plays evaluations here)
For many challenge-based workflows, a hybrid approach works: use starting-balance caps for weekly rules where simplicity matters, and intra-period peak caps for monthly rules where protecting larger runs is a priority. (see our blog)
Practical calculation examples for weekly and monthly drawdown limits
Worked example: calculating a weekly drawdown cap from a percentage
Start with three numbers: the baseline you chose, the percent cap, and the measurement rule. If your starting balance is 1,000 and you set a weekly drawdown limit of 8 percent, the monetary stop is 1,000 times 8 percent, or 80. In this example, a drawdown of 80 or more from the starting balance triggers your stop rule. The math follows the maximum drawdown concept by converting a percent to a concrete loss amount Maximum drawdown formula.
Label each step so you can reproduce it quickly: Baseline, Percent, Monetary Stop, Trigger Condition, Action. Having these labels prevents confusion when the number is close to the threshold and you need to act fast.
compute percent and monetary drawdown for a window
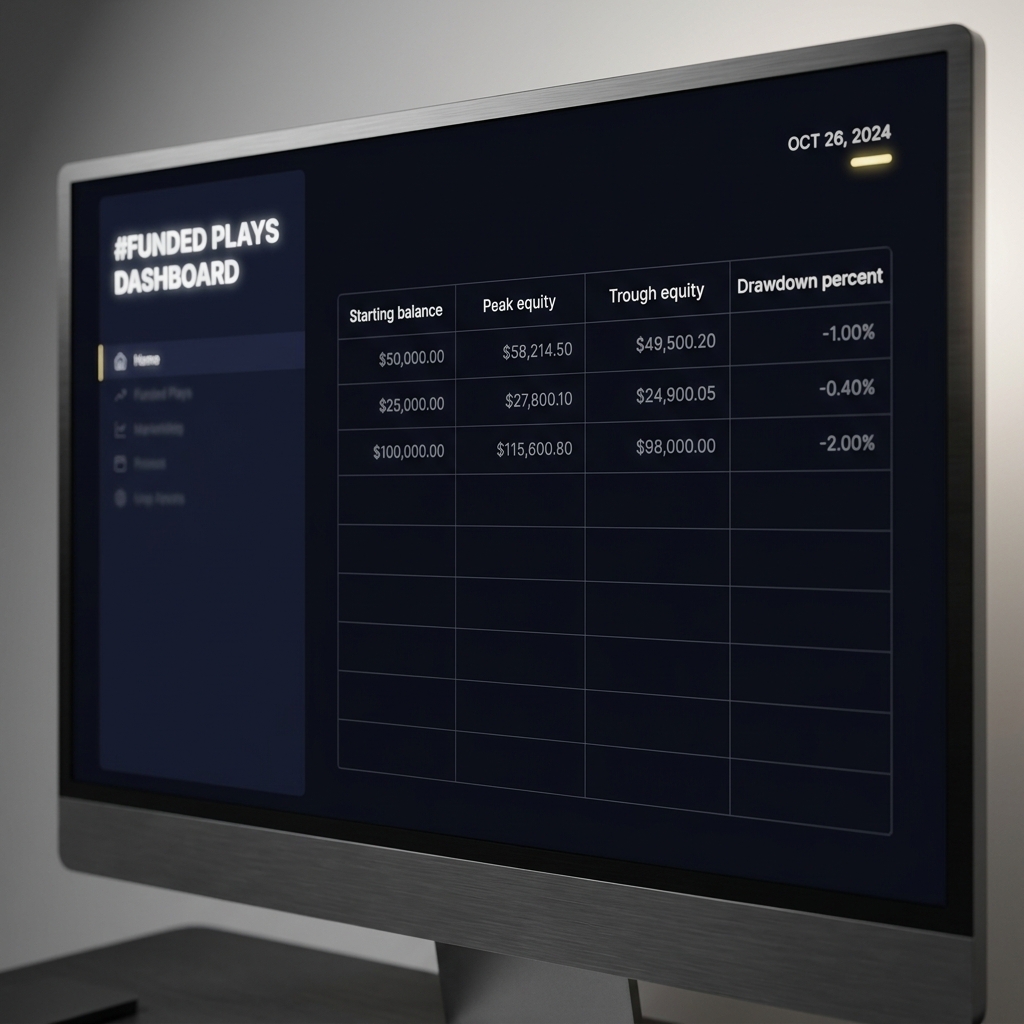
Use consistent sampling for Peak equity
Worked example: monthly drawdown using intra-period peaks
For a monthly cap that uses intra-period peaks, track the highest recorded equity inside the month and the lowest trough after that peak. If the peak is 12,000 and the trough after the peak is 10,200, the drawdown percent equals (10,200 minus 12,000) divided by 12,000, which equals negative 15 percent, or a 15 percent drawdown. This step-by-step computation tracks the peak-to-valley decline and mirrors the academic approach to maximum drawdown calculations Drawdown measure in portfolio optimization.
When you know the drawdown percent, convert it to a monetary stop for communication and automation. For example, a 15 percent monthly cap on a 12,000 baseline equals an 1,800 monetary stop, which can be set as an automated limit or a manual rule to pause activity once that loss is reached.
Translating percentage limits into monetary stops and cooling-off rules
Turn the percent into actions by describing exactly what happens at the trigger: stop predicting for the remainder of the window, reduce stake or prediction size by X percent until the next window, or enter a cooling-off period of Y hours. Writing the action in plain language removes ambiguity when emotions are present.
Also specify how to resume activity after a breach: a passive resume at the next window open, or a review-and-approve step after documenting the breach and the causes. Having a written cooldown and resume plan increases the chance the rule will be followed and allows audit trails for later review Drawdown research context.
How to implement limits in practice: stop rules, platform settings, and regulator-aligned tools
Designing stop rules and scale-down responses
Draft stop rules that are specific and observable, for example: "If weekly drawdown limit equals or exceeds X percent of starting balance, stop activity immediately and record the event." Clear wording removes subjective choices at the moment of stress and ensures consistent responses across users or team members.
Include scale-down alternatives such as halving stake sizes or moving to observation-only mode if you prefer not to stop entirely. Document precise thresholds for each action so you can automate or operationalize them in dashboards and checklists.
Using platform features: limits, time-outs, and dashboards
Modern platforms often support deposit and loss limits, session limits, and time-outs that map directly to pre-commitment rules. Use these built-in features to automate enforcement where possible and reduce the chance of manual overrides that happen under stress Remote gambling technical standards (see restrictions on withdrawals here).
Configure dashboard alerts to notify you when equity approaches a buffer zone near the cap, and set a hard limit that triggers an enforced pause. A two-stage alert and enforcement model helps you act deliberately without surprises.
Regulatory and consumer-protection alignment
Adopting weekly and monthly drawdown caps follows the broader regulatory and consumer-protection trend of encouraging voluntary limits and cooling-off tools as part of safer-play frameworks (in line with major reform of gambling laws announced by government). Documenting and automating these rules aligns user practices with regulator-endorsed approaches to limit-setting PlayMyWay budgeting.
Keep records of limit settings, breaches, and actions taken so you can demonstrate a commitment to responsible participation and learn which thresholds work for your strategy over time. Regulators and programs encourage periodic review and recordkeeping as part of best practice Safer Sports Betting guidance.
Common mistakes and stumbling blocks when using drawdown limits
Setting caps that are too tight or too loose
A common error is choosing caps based on fear or on optimism rather than on historical variance. Caps that are too tight create repeated false triggers that interrupt learning, while caps that are too loose fail to protect against sustained declines. Use past performance to calibrate a sensible starting point and adjust from there based on observed outcomes Drawdown research context.
To correct over-tight limits, add a buffer equal to a reasonable multiple of your average drawdown amplitude; to correct over-loose limits, consider shortening the review cadence so you catch adverse trends sooner.
Confusing horizon mismatches and mixing rules
Mixing calendar and rolling windows or combining inconsistent baselines can produce unexpected results and make action triggers unclear. Keep your weekly and monthly rules distinct and state which baseline each uses to avoid operational confusion.
If you need both a weekly and a monthly rule, state a precedence rule: for example, a monthly cap may remain the ultimate guardrail while weekly caps manage short-term variance.
Ignoring volatility and not allowing for normal variance
Failing to account for inherent strategy volatility will produce false alarms. Measure typical variance and design caps that tolerate ordinary swings while still catching true deteriorations in performance.
When in doubt, perform a conservative backtest to see how often your proposed caps would have triggered in past periods, then adjust to balance protection against unnecessary interruptions Drawdown optimization study.
Monitoring, reviewing, and adjusting limits over time
How often to review weekly and monthly rules
Set a routine review cadence such as monthly for monthly rules and quarterly for the overall program, with the option for ad hoc review after a significant run of breaches or after major strategy changes. Regular reviews help keep caps aligned with changing volatility and objectives.
Document review dates and the rationale for any change so you can trace how rules evolved and why. This recordkeeping is consistent with responsible-play recommendations for periodic limit checks and transparent decision-making Safer Sports Betting guidance.
Using backtesting and performance review to recalibrate caps
Use historical runs and simulated windows to estimate how often a given cap would have triggered and how deep typical drawdowns are, then choose a cap that balances protection and playability. Academic work shows drawdown-aware approaches can reduce downside risk when compared to unconstrained methods, which supports using past data to guide cap choices Drawdown measure in portfolio optimization.
When recalibrating, avoid overfitting to a short period and prefer conservative adjustments that reflect longer-term behavior. Small, documented tweaks are better than frequent large swings in rules.
Documenting changes and maintaining responsible-play records
Keep a short change log that records the date, reason, and new values for any cap change. A simple table with Baseline, Percent Cap, Monetary Cap, Action, and Review Date is often sufficient and makes audits or reviews straightforward.
Recordkeeping demonstrates discipline and supports learning, and it also aligns with the spirit of voluntary budgeting programs that encourage transparent, repeatable limit management PlayMyWay program.
Conclusion and quick checklist to set your weekly and monthly drawdown limits
One-page checklist
Measurement window: choose calendar or rolling
Baseline: starting balance or intra-period peak
Percentage cap and monetary stop: decide and document
Action mapping: stop, scale-down, or cooling-off
Automation: use platform limits and alerts where available
Review cadence: schedule routine checks and backtesting
Next steps and where to find more help
Start by writing your rules, converting percents to monetary stops, and configuring alerts on your dashboard on Funded Plays (see recent reporting here). Keep records and review results after each cycle to refine the caps.
Drawdown controls are pre-commitment safety tools that support disciplined participation; they reduce downside risk when combined with good recordkeeping and sensible review practices.
Multiply the baseline amount by the percentage cap to get the monetary stop; document the baseline and sampling rule so the number is unambiguous.
Use starting balance for simplicity and intra-period peak when you need to protect gains and measure peak-to-valley declines; a hybrid approach can also work.
Review monthly for monthly rules and quarterly for program-level adjustments, with ad hoc reviews after significant breaches or strategy changes.
References
- https://www.ecfr.gov/current/title-17/chapter-I/part-4/section-4.10
- https://www.investopedia.com/terms/m/maximum-drawdown-mdd.asp
- https://www.responsibleplay.org/safer-sports-betting/
- https://massgaming.com/responsible-gaming/playmyway/
- https://www.gamblingcommission.gov.uk/technical-standards/remote-gambling-and-software-technical-standards
- https://www.fundedplays.com/challenges
- https://www.fundedplays.com/blogs/how-fundedplays-evaluations-work
- https://www.fundedplays.com/blogs
- https://www.fundedplays.com
- https://www.worldscientific.com/doi/abs/10.1142/S0219024905002767
- https://www.gamblingcommission.gov.uk/licensees-and-businesses/guide/page/restrictions-on-withdrawing-deposit-and-deposit-winnings
- https://www.gov.uk/government/news/major-reform-of-gambling-laws-to-protect-vulnerable-users-in-smartphone-era
- https://www.bbc.co.uk/news/articles/cqj1xvy44xno