
What 'american express odds' means and how this relates to a $100,000 card capacity
When people ask about american express odds for a six figure charge, they are usually asking how likely American Express is to approve a very large purchase for a consumer account. In practice the phrase describes the practical likelihood of approval based on account history and issuer judgement rather than a published numeric cap.
No Preset Spending Limit, or NPSL, is a common way issuers such as American Express describe charge products that do not show a fixed revolving line. NPSL means purchasing power adjusts with your payment history, credit profile, and recent activity rather than operating from a fixed, reusable dollar limit; this distinction is explained in a clear industry overview on NPSL Investopedia guide to NPSL. Also see the American Express description of No Preset Spending Limit No Preset Spending Limit.
U.S. consumer cards rarely publish a fixed $100,000 limit. Market research shows typical per-card limits for most consumers are generally far below six figures, so a headline figure of one hundred thousand dollars does not represent a standard offer and is uncommon for ordinary consumer accounts Experian state of credit.

To put it another way, american express odds are really an assessment of whether your account profile, recent payments, and overall relationship with the issuer point toward approval for a large one-off charge. American Express offers tools and account features that help make that assessment more predictable, but they do not amount to an automatic guarantee of approval. Visit Funded Plays for related resources.
Because six figure capacity is profile dependent, people with exceptional credit, long positive histories, significant income, and low existing obligations may see much higher practical purchasing power than the average consumer. Still, issuers do not usually advertise a public $100,000 consumer limit, so asking about a $100,000 card is mostly about understanding tailored approval odds rather than expecting a fixed advertised cap.

How American Express handles large purchases: Check Spending Power and Pay Over Time
If you are planning a single large purchase, the most direct tool American Express provides is the Check Spending Power feature, which lets cardholders simulate or request a quick estimate of whether a specific transaction would be approved. Using that tool can reduce uncertainty by testing one planned charge before you commit to it American Express Check Spending Power.
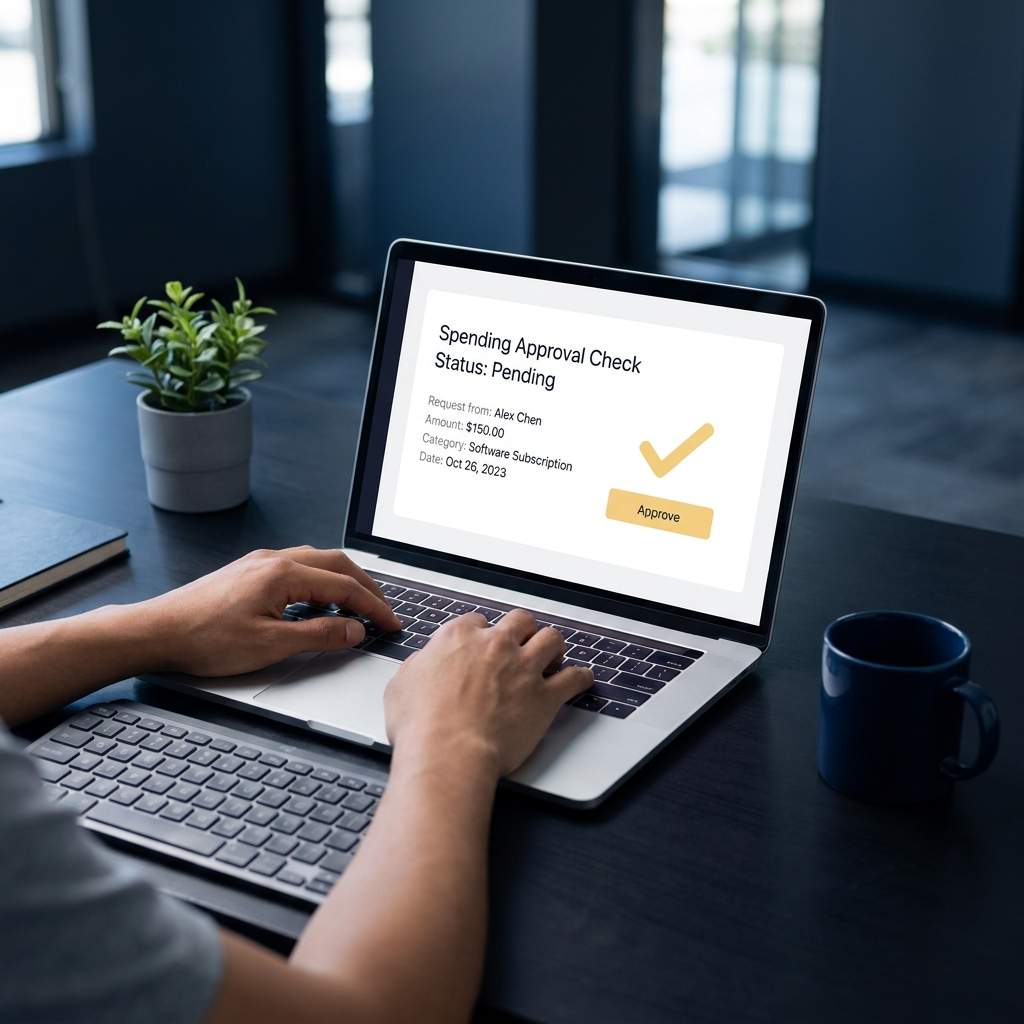
Check Spending Power is intended for single transactions. It gives a near-term sense of approval likelihood based on your account activity and profile, and it is especially useful for planned purchases that feel near or above your usual activity level. Running a check does not create a permanent change to your account; it simply gives a decision or estimate for that charge attempt.
Separate from that single-transaction check, certain eligible American Express cards offer a Pay Over Time option that allows qualifying purchases to be revolved rather than paid in full immediately. Pay Over Time is not the same as giving the card a fixed, unlimited credit line, and using it still operates within the issuer's broader capacity assessment and account rules American Express Pay Over Time.
When you use Pay Over Time on a card that otherwise has NPSL characteristics, the purchase may be revolvable if it meets the program criteria, but that does not convert NPSL into a fixed, reusable credit limit. The issuer still evaluates risk factors to decide what spending is allowed and whether balances can be carried, so Pay Over Time provides flexibility without negating the dynamic nature of NPSL.
In short, Check Spending Power helps you gauge whether a specific six figure purchase would likely be accepted, and Pay Over Time may let you carry certain eligible balances. Both tools improve predictability compared with guessing, but neither substitutes for the issuer's ongoing risk assessment that determines overall capacity.
How issuers decide limits and what improves your chances
Issuers use several underwriting factors when they decide how much capacity to allow on an account. The main inputs include credit score, payment history, income and employment information, existing debt obligations, and current credit utilization, all of which influence an issuer's risk view FICO explanation of score components.
Good payment history and low utilization are two of the most actionable items consumers can control. Consistently paying on time and keeping revolving balances low signals responsible account behavior, and over time that track record tends to increase the odds for larger approvals or more generous purchasing power from issuers.
There are formal steps you can take when you want more capacity. Where a card has a stated credit line, you can request a credit limit increase and provide updated income or employment information to support the request. For charge products, building longer-term positive payment behavior and a relationship history helps the issuer rely on your record when assessing high-value purchase approvals Experian guide to high limit cards.
Practical habits that help improve approval odds include documenting income accurately, avoiding sudden spikes in utilization just before a request, and allowing several billing cycles of consistent payments after any major balance is paid down. Each of these reduces perceived risk and gives the issuer more confidence in extending higher practical capacity.
Try issuer tools to estimate approval for large purchases
Use these steps before making a large charge
If you plan to make a very large purchase, combine a request for a pre-transaction check with good documentation and a calm cadence of spending. That combination helps you present a lower-risk picture to the issuer and increases the practical american express odds of approval for an individual charge. For practical examples see the Funded Plays blog.
Charge card NPSL versus revolving credit cards: practical differences for big purchases
Charge cards with No Preset Spending Limit, commonly associated with some American Express products, do not report a fixed, reusable credit line to cardholders. Instead they rely on dynamic capacity that adjusts based on spending patterns, payment history, and other risk signals; this practical difference between a dynamic approach and a fixed line is explained in industry guidance on NPSL Investopedia guide to NPSL.
Revolving credit cards typically show a numerical credit limit you can reuse as you pay down balances. That fixed line makes it easier to know your available capacity ahead of time, but many revolving limits for consumers fall well short of six figures. In contrast, an NPSL product may permit a one-off purchase that exceeds what a revolving card would allow because the issuer makes a judgement about that specific charge in context.
Some Amex charge cards allow eligible purchases to be enrolled in Pay Over Time so you can carry balances for qualifying charges. Even when Pay Over Time is available, the underlying spending capacity remains dynamic and subject to the issuer's ongoing assessment, so combining the two features can increase flexibility for large purchases without changing the account into a traditional fixed-limit card American Express Pay Over Time.
Put simply, charge products can offer higher single-transaction purchasing power for qualified cardholders because the issuer considers the context of the charge rather than relying on a posted limit. But that situational advantage depends on the issuer's judgement and the cardholder's profile, so it is not a guaranteed path to six figure approvals for everyone.
Typical limits in the market and what the data shows about six figure capacity
Broad market research finds that typical consumer credit card limits are usually far below six figures for most people. This means that $100,000 purchasing capacity is uncommon and generally reserved for exceptional profiles or business-focused products rather than typical consumer offers Experian state of credit.
Exceptional profiles often combine long account histories, very strong credit scores, significant documented income, low overall debt, and relationships with the issuer. Those factors together create the conditions where an issuer may approve a much larger single transaction or afford higher ongoing capacity, but this remains the exception rather than the rule.
A $100,000 approval is possible for some cardholders but not guaranteed; American Express uses dynamic capacity for many charge products and offers tools like Check Spending Power to test specific transactions.
If you are wondering whether a six figure limit is realistic for your situation, the answer usually depends on whether your profile matches those exceptional characteristics and whether the issuer views the planned charge as low risk for that account. Because published limits at the consumer level rarely list six figures, the realistic view of american express odds is about profile and context rather than a standard threshold.
Business NPSL accounts and certain corporate charge products often have different underwriting frameworks and can present higher published or implicit capacity than consumer cards. If you routinely need very high purchasing power for business reasons, evaluating business NPSL or corporate payment solutions is a practical step to explore. See our writeup on how Funded Plays evaluations work how-fundedplays-evaluations-work.
Practical steps to test or secure capacity for a planned large purchase
Before the purchase, run American Express Check Spending Power for the specific transaction you have in mind. That test gives a near-term estimate of whether the charge, at the planned amount, is likely to be approved and reduces guesswork about american express odds for that one charge American Express Check Spending Power.
Also gather supporting documentation such as recent pay stubs or account statements and be prepared to supply updated income if you request a formal limit increase. Presenting clear, current financial information supports the issuer's review and can improve the chance of a favorable decision when you seek higher capacity.

If you need more capacity and Check Spending Power indicates a possible decline, consider alternatives: ask about a one time preauthorization for the merchant, split the payment across multiple cards or methods, coordinate prepayment to free up capacity, or evaluate a business-focused NPSL product that matches your spending needs. These practical choices can let you complete a purchase even if a single consumer card cannot cover it Experian guide to options for high limits.
Keep in mind that formal requests for increases, large sudden charges, or repeated high-amount activity may trigger underwriting reviews. These reviews are a normal part of risk management; they can slow a transaction or produce declines in some cases, so plan for potential delays and avoid last-minute reliance on uncertain approvals American Express Pay Over Time.
Common mistakes, risks, and compliance considerations
A few common mistakes can make large-purchase outcomes worse. One is assuming that No Preset Spending Limit means unlimited spending. NPSL products provide dynamic capacity, not an open checkbook, and treating them as unlimited can lead to declines or account reviews if the issuer sees unexpected risk Investopedia guide to NPSL.
Another common error is skipping a pre-check such as Check Spending Power before attempting a large charge. Failing to test a transaction in advance increases the chance of a declined payment at the point of sale and the associated inconvenience American Express Check Spending Power.
Explore structured challenge options on FundedPlays
Test large purchases in advance and avoid assuming any card provides unlimited capacity; use issuer tools and responsible planning to reduce the risk of declines.
Carrying high utilization or making sudden spending spikes can hurt your long-term approval prospects. High utilization and late payments affect credit scoring and issuer risk models, so if you want better odds for significant purchases, maintain lower utilization and a clean payment history over several cycles FICO explanation of score components.
Finally, keep compliance in mind for large business payments or regulated purchases. Some merchants and issuers require additional verification for very large transactions, so be ready to provide documentation and allow time for review rather than assuming an immediate authorization.
Conclusion: realistic expectations and next steps
To summarize, no major U.S. issuer publicly guarantees a $100,000 consumer card limit, and No Preset Spending Limit products provide variable purchasing power that depends on account history and issuer judgement rather than a set numeric cap Investopedia guide to NPSL.
If you are planning a large purchase, use American Express Check Spending Power to get a specific read on that transaction and follow sound credit practices such as timely payments and low utilization to improve your practical approval odds American Express Check Spending Power.
Remember that outcomes depend on individual account risk and issuer discretion, so treat any single example as an illustration rather than a promise. If you regularly need very high purchasing power for business purposes, consider evaluating business NPSL products or preauthorization approaches as alternative solutions.
Taking careful, documented steps and using the issuer tools available will give you the clearest picture of american express odds for a large charge and help you complete important purchases with less surprise.
No major U.S. issuer usually publishes a $100,000 fixed consumer card limit; high purchasing power is typically profile dependent and often tied to NPSL or business products.
It means spending capacity is dynamic and based on account history and issuer assessment, not an unlimited or fixed numeric line.
Use issuer tools such as American Express Check Spending Power, gather documentation, and consider preauthorization or split payments if needed.
References
- https://www.americanexpress.com/us/customer-service/digital/check-spending-power.html
- https://www.investopedia.com/terms/n/no-preset-spending-limit-npsl.asp
- https://www.experian.com/blogs/ask-experian/research/state-of-credit/
- https://www.fundedplays.com/challenges
- https://www.americanexpress.com/en-us/account/services/check-spending-power
- https://www.americanexpress.com/us/credit-cards/features-benefits/pay-over-time/
- https://www.myfico.com/credit-education/whats-in-your-credit-score
- https://www.experian.com/blogs/ask-experian/what-is-a-high-limit-credit-card/
- https://www.americanexpress.com/en-us/banking/lending/lending-options/no-preset-spending-limit.html
- https://www.americanexpress.com/en-us/business/trends-and-insights/videos/no-preset-spending-limit-npsl/
- https://www.fundedplays.com
- https://www.fundedplays.com/blogs
- https://www.fundedplays.com/blogs/how-fundedplays-evaluations-work